
Post-Graduate Stories
Guneet Singh Dhillon Will Develop New Methods Using “E-Values for Data Science and Risk Management”
As a 2026 CANSSI Distinguished Postdoctoral Fellow, Guneet Singh Dhillon will take part in a comprehensive program that involves teaching, interdisciplinary or applied collaboration, professional development, and a research project focusing on the development of new tools and methods using e-values as an alternative to p-values for data science and risk management applications. Guneet will work under the supervision of Professors Ruodu Wang (University of Waterloo) and Christopher Blier-Wong (University of Toronto).
Program: CANSSI Distinguished Postdoctoral Fellowships
Region: National
Date: 2026–2028
Project Focus Areas
Guneet’s work will focus on developing new tools for data science and risk management using e-values, a modern alternative to p-values with strong theoretical guarantees.
Traditional approaches often rely on unrealistic assumptions and cannot handle continuous monitoring or complex dependence. E-values can provide valid and safe inferences in these settings. Guneet will make significant advances towards e-value methods for data science and risk management applications, such as multiple testing of risk measures and sequential testing for modern machine learning systems, promising substantial impact on data science and risk management frameworks.
He will engage in immersive applied collaborations that connect statistical innovation with real-world problems and will interact with leading researchers in statistics and machine learning, particularly the growing e-value community. Guneet will also engage to advise on implementing the developed tools.
In addition to conducting collaborative research, Guneet will teach statistics courses, participate in development workshops, and gain professional experience by supervising students and presenting at conferences.
Getting to Know Guneet
Guneet Singh Dhillon completed his DPhil in Statistics at the University of Oxford (2021–2026), where his research focused on the robustness of modern predictive and generative machine learning systems. He was supervised by Professors Yee Whye Teh, Tom Rainforth, George Deligiannidis, and Arnaud Doucet, and was also awarded the Clarendon Fund Scholarship.
Before his DPhil, Guneet spent three years as an Applied Scientist at Amazon Web Services (2018–2021). He received a BSc in Computer Science (Honors and Turing Scholars Honors) and a BSc in Mathematics (Honors) from the University of Texas at Austin (2014–2018), where he also completed a certificate in Applied Statistical Modeling, a minor in Economics, and an honors thesis supervised by Professor Adam Klivans.
Guneet aspires to “become an independent researcher in the statistical sciences, with an emphasis on practical theory, that is, developing meaningful theoretical work with tangible real-world impact.” Through the CANSSI Distinguished Postdoctoral Fellowship, he aims to “engage in interdisciplinary collaborations that bridge statistics with other scientific fields” and to take the opportunity to “teach and mentor the next generation of researchers.”
The CANSSI Distinguished Postdoctoral Fellowship places strong emphasis on interdisciplinary projects with applied components, aligning closely with my research ambitions.
About the Supervisors
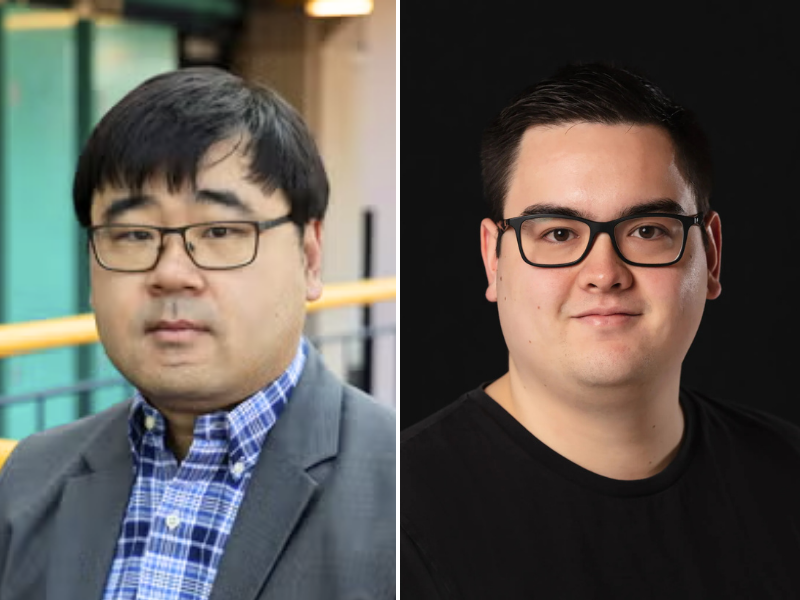
Ruodu Wang
Dr. Ruodu Wang is Tier 1 Canada Research Chair in Quantitative Risk Management and Professor of Actuarial Science and Quantitative Finance at the University of Waterloo. He received his PhD in Mathematics (2012) from the Georgia Institute of Technology, after completing his bachelor’s (2006) and master’s (2009) degrees at Peking University. He holds editorial positions in eight leading journals in actuarial science, operations research, statistics, and economics, including Co-Editor of ASTIN Bulletin – The Journal of the International Actuarial Association and Co-Editor of the European Actuarial Journal. Among other international awards and recognitions, he is the first winner of the SOA Actuarial Science Early Career Award (2021) from the Society of Actuaries, and a Fellow of the Institute of Mathematical Statistics (elected 2022). His research papers are published in top journals across a wide range of scientific fields, such as the American Economic Review, the Annals of Statistics, the Journal of the Royal Statistical Society (Series B), Management Science, Operations Research, and the Proceedings of the National Academy of Sciences.
Christopher Blier-Wong
Christopher Blier-Wong is an Assistant Professor of Actuarial Science at the University of Toronto, where he develops theory and methods for dependence modelling, risk sharing, machine learning in insurance, and assumption-lean hypothesis testing. His research includes copula theory, collective risk models, sequential and anytime-valid inference, machine learning for pricing, and robust optimization under model uncertainty. He often collaborates with industry partners on problems motivated by practical challenges in insurance. His publications appear in leading journals across actuarial science and statistics.
Explore More Stories
 National Region
 National Region
 National Region
 National Region
 National Region